You have been Successfully Subscribed to Newsletter


What is CPA Cover in Car Insurance? Coverage & Benefits Explained
June 10, 2026 • 10 Min Read
Compulsory Personal Accident (CPA) cover is mandatory protection for car owners (Owner/Driver) in India, providing ₹15 lakh compensation for accidental death or permanent disability. The CPA cover in car insurance means financial security for owner-drivers with affordable annual premiums. This coverage works regardless of fault, offers protection, and, if you own two or more vehicles, you only need one valid CPA cover (typically as a standalone policy); it protects you as the owner-driver in the event of an accident involving any vehicle registered in your name, without requiring separate coverage for each policy.
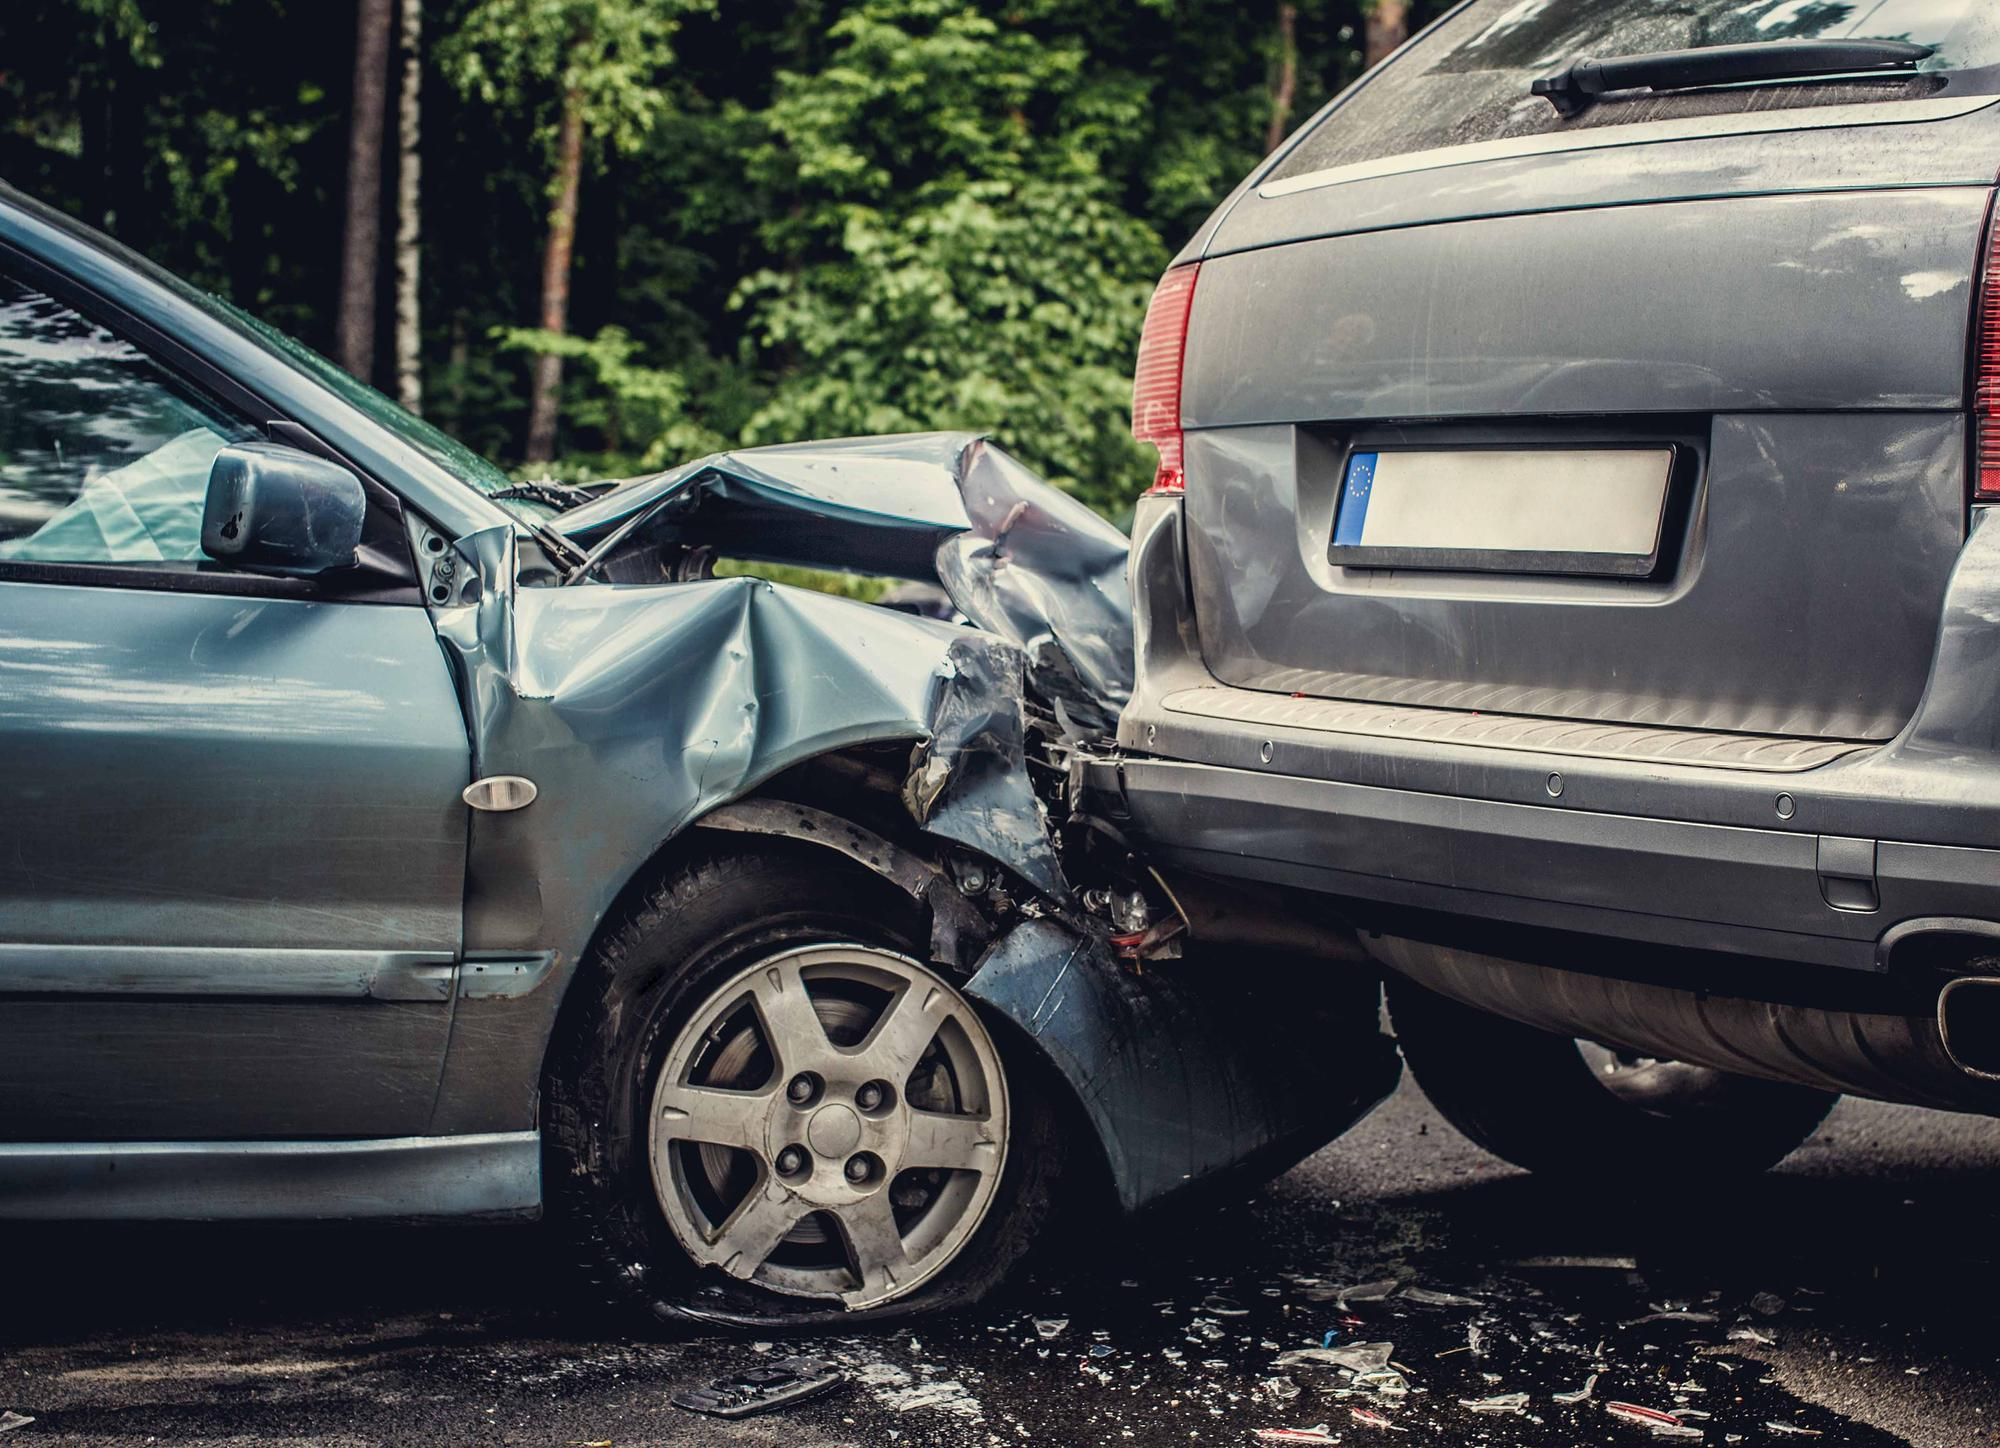
Every car journey carries inherent risks, from minor fender-benders to serious accidents. Compulsory Personal Accident (CPA) cover acts as a mandatory financial safety net specifically for the owner-driver in India. As per IRDAI rules, it provides ₹15 lakh compensation in case of accidental death or permanent disability while driving the insured vehicle (including mounting/dismounting or travelling as a co-driver). This coverage applies regardless of fault and helps protect your family from financial hardship.
Unlike a general personal accident policy (which can cover slips, falls, or incidents worldwide), CPA is tied to motor insurance and focuses on the owner-driver. If you own multiple vehicles, like a car and a scooter, you only need one valid CPA cover (often as a standalone policy). When buying insurance for another vehicle, you can declare the existing cover and skip duplicating it, ensuring protection remains active even if an accident occurs while driving any of your registered vehicles.
Understanding CPA Cover in Car Insurance
Grasp CPA's role, legal mandates, and coverage scope for owner-driver protection in Indian motor insurance.
Definition of CPA Cover
Many vehicle owners often ask, "What is CPA cover in car insurance, and why is it mandatory?" Compulsory Personal Accident (CPA) cover is a required part of motor insurance in India for owner-drivers, as outlined in the Motor Vehicles Act of 1988 and enforced by IRDAI regulations. This coverage provides financial protection to the registered owner-driver in the event of accidental death or permanent disability while driving.
Understand what CPA covers in car insurance, which centres on human life protection, not vehicle damage. As per IRDAI guidelines, it offers compensation up to ₹15 lakh (with the exact amount depending on the severity of the injury or accident) to the insured owner-driver or their nominee if a serious accident leads to death or permanent disability. The benefit is straightforward and does not involve depreciation calculations or complex loss assessments, providing a clear lump-sum financial safety net focused solely on the owner-driver's accidental death or specified permanent disabilities arising from the insured vehicle.
Legal Mandate and IRDAI Guidelines
The Insurance Regulatory and Development Authority of India (IRDAI) made CPA cover for ₹15 Lakhs to own driver is mandatory under the Motor Vehicles Act, effective January 2019.
Key regulatory updates include:
- Minimum coverage increased to ₹15 lakh (earlier ₹1–2 lakh).
- Option to buy standalone CPA policies.
- Exemption allowed if the owner already has a personal accident policy of at least ₹15 lakh.
This ensures every vehicle owner has basic accident protection while avoiding duplicate coverage.
Who Is Covered Under CPA
CPA cover applies to:
- The registered vehicle owner
- Holding a valid driving licence
- Named in the policy
It does not cover:
- Insured or consented drivers under the influence of liquor/drugs.
- Owner-driver without a valid license.
- Non-compliant permitted drivers violating policy terms.
- Persons using vehicle outside policy limits or by unapproved drivers.
If purchased as a standalone policy, it can cover all vehicles owned by the same individual under one policy.
Benefits of CPA Cover
CPA delivers high-value financial security for owner-drivers at minimal premiums amid India's rising road accidents.
Financial Protection for Owner-Driver
CPA provides immediate financial support in case of death or permanent disability.
- In case of death: nominee receives ₹15 lakh.
- In case of permanent total disability: insured receives ₹15 lakh.
- In case of partial permanent disability: 50% of the sum insured.
Given India’s high accident rates, this protection plays a critical role in securing a family’s financial stability.
Coverage Amount and Affordability
CPA cover offers high protection at a low cost:
|
|
|
|
|---|---|---|
| Pre-2017 | ₹50–₹100 | ₹1–2 lakh |
| 2017–Present | Variable, based on rating factors. | ₹15 lakh |
Disclaimer: Premiums are indicative and subject to change.
Universal Protection Regardless of Fault
CPA (Compulsory Personal Accident) cover operates on a no-fault basis, ensuring protection regardless of who caused the accident. It applies across India and covers incidents even if the vehicle sustains minimal damage. Compensation is disbursed swiftly without the need for prolonged legal disputes over liability. The only exceptions are intentional self-harm like suicide, accidents under the influence of alcohol or drugs, or incidents outside defined geographical limits.
Coverage and Renewability
Standalone CPA policies typically offer ₹15 lakh coverage, lifelong renewability, and flexible tenures as per your base motor policy.
Coverage Details Under CPA
CPA provides fixed payouts for accidental death or permanent disabilities, scaled by severity up to ₹15 lakh sum insured.
Accidental Death Compensation
If the owner-driver dies due to an accident:
- 100% of the sum insured (₹15 lakh) is paid to the nominee.
- Death/disablement must occur immediately or within 6 months due to accident injuries independent of any other cause.
Required documents typically include an FIR, post-mortem report, and death certificate.
Permanent Total and Partial Disability Compensation
Compensation depends on severity:
|
|
|
|
|---|---|---|
| Loss of two limbs | 100% | ₹15 lakh |
| Loss of sight in both eyes | 100% | ₹15 lakh |
| Loss of one limb or sight of one eye | 50% | ₹7.5 lakh |
| Loss of two limbs or sight of two eyes, or one limb and sight of one eye | 100% | ₹15 lakh |
| Other total permanent disability | 100% | ₹15 lakh |
Disclaimer: Compensation is based on medical evaluation and policy terms.
Note: Disability must be confirmed within 6 months of the accident.
Compensation Scale and Examples
For example:
- Loss of one arm → ₹7.5 lakh
- Loss of both arms → ₹15 lakh
Medical certificates from recognised authorities are mandatory to establish eligibility.
Exclusions and Limitations of CPA Cover
Know key exclusions like self-harm, driving under the influence (DUI), and temporary injuries to avoid claim rejections under CPA policies.
Intentional Self-Harm or Suicide
CPA does not cover:
- Suicide
- Attempted suicide
- Intentional self-harm
Claims are investigated thoroughly before approval.
Driving Under the Influence of Alcohol or Drugs
No coverage if the insured was:
- Driving under the influence of alcohol
- Driving under the influence of narcotics or intoxicants
Blood Alcohol Concentration (BAC) reports and police findings determine eligibility.
Temporary Injuries and Non-covered Expenses
CPA does not cover:
- Temporary injuries
- Medical bills
- Hospital expenses
- Rehabilitation costs
- Income loss during recovery
It strictly compensates for death or permanent disability.
Other exclusions include:
- Invalid driving licence
- Illegal activities
- War or nuclear risks
Standalone CPA Policy vs CPA Included in Motor Insurance
Choose a standalone CPA for multi-vehicle coverage and renewal flexibility over bundled motor insurance add-ons.
When to Opt for Standalone CPA Cover
Standalone CPA is beneficial if:
- You own multiple vehicles
- You want to avoid duplicate coverage
- You want flexibility independent of motor insurance renewal
Coverage across Multiple Vehicles
A standalone CPA policy can cover all vehicles owned by one individual under a single policy.
For example:
- Car + bike + scooter → one CPA policy is sufficient.
This significantly reduces costs compared to buying a CPA separately for each vehicle.
Benefits of Standalone CPA Policy
Advantages include:
- Coverage portability across vehicles
- Flexible tenure
- Possible additional benefits
- Independent renewal cycle
It provides broader flexibility compared to bundled CPA.
How to Claim CPA Cover in Car Insurance
Follow this streamlined process and prepare key documents for a quick CPA claim settlement in car insurance.
Step-by-Step Claim Process
- Inform the insurer immediately (within 24–72 hours).
- Provide accident details and policy information.
- Submit required documents.
- Insurer verifies through survey and documentation review.
- Compensation is processed as per policy terms.
Required Documents for Claim
Key documents include:
- FIR copy
- Valid driving licence
- Vehicle RC
- Policy document
- Medical records
- Death or disability certificate
- KYC documents
- Cancelled cheque
- Nominee ID proof
Additional documents may be requested based on case specifics.
Tips for Faster Claim Settlement
- Report immediately.
- Maintain organised documentation.
- Ensure nomination details are updated.
- Follow up regularly with the insurer.
Timely and complete submission reduces processing delays.
Who Needs CPA Cover and Policy Duration
Understand CPA's mandatory status, exemptions, and flexible policy tenures for seamless coverage.
Mandatory Nature and Owner-Driver Requirement
CPA is mandatory for:
- All vehicle owners
- Third-party and comprehensive policies alike
Exemption applies only if:
- A personal accident policy of at least ₹15 lakh already exists.
Non-compliance may result in penalties or policy issues.
Policy Tenure Options and Renewal
Policy durations:
- Cars: 1–3 years
- Two-wheelers: up to 5 years
Renewal reminders are typically sent 30–45 days before expiry. Continuous renewal ensures uninterrupted coverage.
Relation with Standalone Personal Accident Policies
If you already have a personal accident policy of ₹15 lakh or more, you may request exemption from buying additional CPA. However, review coverage carefully to avoid gaps, as some policies may exclude motor-related accidents.
Comprehensive Protection Beyond CPA Coverage
Royal Sundaram car insurance goes beyond mandatory ₹15 lakh CPA coverage with zero depreciation, engine protection, and key replacement add-ons, all in one policy for complete vehicle and personal protection. Royal Sundaram's digital platform lets you buy, renew, and manage policies online, with low premiums, making comprehensive coverage affordable for all car owners.
Enjoy 24x7 claim support, a streamlined process, and 8000+ garage networks to minimise accident hassles. Enquire about Royal Sundaram's comprehensive car insurance today.
Common Questions About CPA Cover
Yes, compulsory personal accident cover is mandatory for all motor vehicles like your car or two wheeler insurance policies (owner/drivers) in India as per the Motor Vehicles Act and IRDAI regulations. You cannot opt out unless you have equivalent standalone personal accident coverage worth at least ₹15 lakh.
CPA cover in car insurance includes financial protection for accidental death (100% of ₹15 lakh), permanent total disability (100%), and partial permanent disability (50% for loss of one limb or one eye). It covers only the registered owner-driver of the vehicle.
You cannot opt out of CPA cover unless you possess a standalone personal accident policy providing at least ₹15 lakh coverage. This exemption prevents duplicate coverage while ensuring legal compliance with mandatory accident protection requirements.
Compensation depends on injury severity: 100% of the sum insured (₹15 lakh) for death or total permanent disability, and 50% (₹7.5 lakh) for loss of one limb or sight in one eye. The calculation follows standardised medical guidelines for disability assessment.
Key exclusions include intentional self-harm, suicide, driving under the influence of alcohol or drugs, accidents outside geographical limits, temporary injuries, invalid driving licence scenarios, and commercial vehicle use for illegal purposes.
Essential documents include an FIR copy, medical records, death/disability certificate, valid driving licence, vehicle registration, policy documents, income proof, KYC documents, and a cancelled cheque for compensation disbursement to nominees.
Standalone CPA policies cover multiple vehicles under one policy, offer greater flexibility, and can be purchased independently. Bundled CPA coverage applies only to the specific insured vehicle and renews with motor insurance policies.
CPA policies typically last 1-3 years for cars and up to 5 years for motorcycles. They offer lifelong renewability options, allowing continuous protection throughout your driving years with flexible renewal schedules.

Discover the perfect insurance plan for you!
Get your free quote now!
Get StartedBy Clicking on Get Started, You agree to our Terms and Conditions and override DNC/NDNC registration.
More like this
View more